

What Is a Flexi Loan and How Does It Work?
A flexi loan is a borrowing product with flexible withdrawal or repayment features. Some products provide a reusable credit limit: you draw money when needed, repay it, and may draw again within the available limit. Others are term loans with particular repayment options. The word “flexi” alone does not tell you which arrangement you are getting.
The useful question is therefore not simply whether a loan is flexible. It is what happens to your outstanding balance, interest, available limit and repayment obligation after every withdrawal and payment. Those mechanics determine whether the facility suits your cash flow and whether its flexibility is worth the fees.
Key takeaways
- “Flexi” describes a feature, not a complete set of loan terms: check whether the contract is a reusable credit limit, a term loan with flexible features or a dropline facility.
- A sanctioned limit is permission to borrow, not money you own; every withdrawal increases principal outstanding.
- Only the part of a payment allocated to principal reduces the debt; an interest-only payment leaves principal unchanged.
- Interest may be charged on the utilised balance, but facility, maintenance and other charges can depend on the sanctioned limit.
- Repaid principal can be reused only if the contract permits redraw, and a dropline limit can reduce headroom even when every payment is on time.
- Compare the total cost of your expected borrowing pattern with a standard term loan rather than relying on a headline rate or a single EMI.
At a glance: A sanctioned limit is permission to borrow, not money you own. In a drawdown facility, interest may depend on the amount actually outstanding, while other charges can depend on the sanctioned limit. Redraw rights and principal repayment must be checked separately.
What does the word flexi actually mean?
"Flexi" describes a feature rather than a complete set of loan terms. A lender may use the label for access to funds in stages, the ability to make additional repayments, an initial interest-only period, or a combination of these features. Two products using the same label can therefore behave differently.
Start with the sanction letter and agreement. Identify whether the contract describes a term loan, an overdraft or another credit facility. Then establish how funds reach you and how the debt must reduce. An attractive product name cannot replace those answers.
A reusable credit limit
A revolving arrangement lets you borrow up to an approved ceiling, repay, and potentially reuse the repaid principal. Access remains subject to the agreement, the facility being active and any restrictions or reviews. It does not mean every payment immediately restores the same amount of spending power.
The distinction between principal and interest is important. Paying interest settles the cost of borrowing for a period; it does not repay the money you borrowed. Only the part allocated to principal reduces principal outstanding. Fees and overdue amounts can also affect how a payment is allocated.
A term loan with flexible features
A term loan may allow additional repayments or an initial period of lower payments without giving you a reusable line of credit. If the lender disburses the full loan at the start, leaving some of it unspent in your savings account does not normally make that portion undisbursed.
Ask whether money is genuinely available for later drawdown or has already been advanced. If the full principal has been disbursed, interest may accrue on the outstanding loan balance even while you have not spent all the cash. That is different from charging interest on an unused credit limit.
A dropline or reducing-limit facility
A dropline arrangement reduces the permitted borrowing ceiling according to a schedule. Repaying principal can create room to borrow again, but the ceiling may also be falling. Your current limit, rather than the original sanction, governs access.
These features can overlap. A facility may permit redraws and still have a dropline schedule. Another may combine an interest-only phase with later principal instalments. Understand each feature on its own before judging the package.
How do withdrawals, repayments and available credit interact?
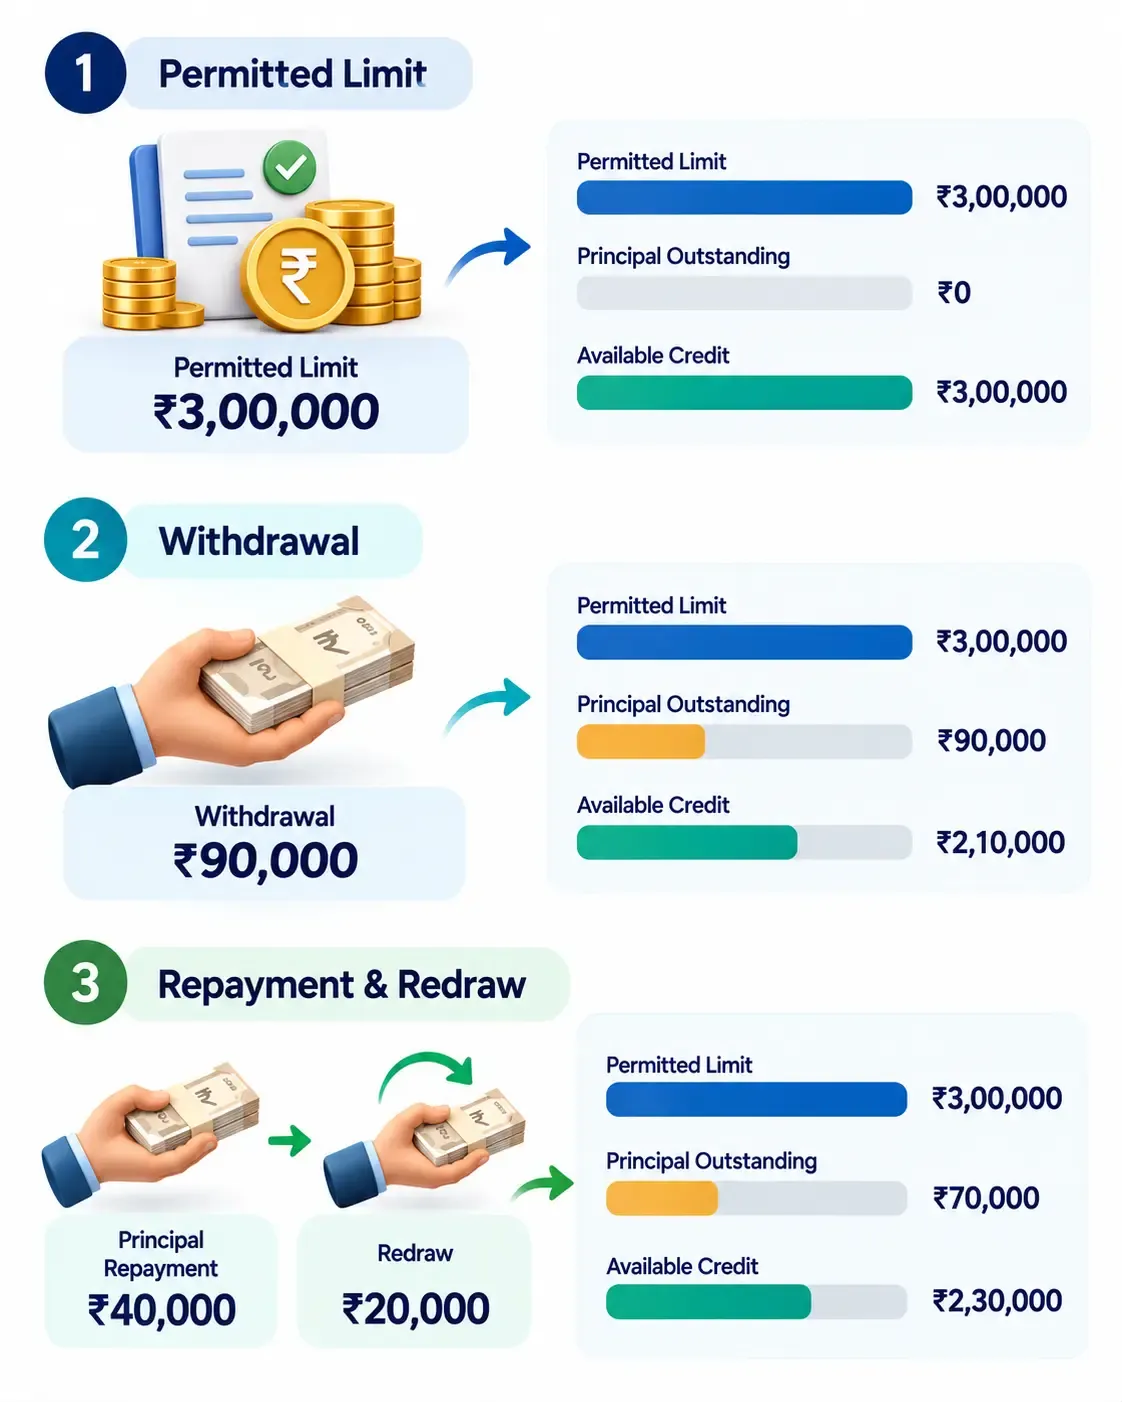
In a drawdown-based flexi facility, withdrawing money increases principal outstanding. A payment allocated to principal reduces it. Available credit then depends on the current permitted limit, outstanding principal, and any holds or contractual restrictions.
A simplified relationship is:
Available credit = current permitted limit − principal outstanding, before any additional restrictions.
This is a useful checking tool, not a substitute for the lender's account statement. A pending transaction, overdue payment or scheduled limit reduction can make the amount available for immediate withdrawal smaller.
Follow the account through a simple example
The following is an illustrative revolving facility with a constant ₹3,00,000 limit. It assumes no fees, holds, overdue amounts or restrictions and immediate recognition of principal repayments. These are teaching assumptions, not an offer.
| Event | Principal outstanding | Available credit |
|---|---|---|
| Limit activated; nothing drawn | ₹0 | ₹3,00,000 |
| First withdrawal of ₹90,000 | ₹90,000 | ₹2,10,000 |
| Second withdrawal of ₹30,000 | ₹1,20,000 | ₹1,80,000 |
| Principal repayment of ₹40,000 | ₹80,000 | ₹2,20,000 |
| Further withdrawal of ₹20,000 | ₹1,00,000 | ₹2,00,000 |
After the final event, the borrower owes ₹1,00,000 of principal. They do not owe the cumulative ₹1,40,000 withdrawn because ₹40,000 has been repaid. Conversely, the remaining ₹2,00,000 is not savings: withdrawing it would increase debt.
If the ₹40,000 payment included interest or charges, the principal reduction would be smaller. Check the allocation on the statement rather than assuming that every rupee paid has restored credit.
Why the payment date matters
If interest is calculated using daily outstanding balances, an earlier recognised principal repayment can reduce subsequent interest. Sending money is not necessarily the same as its effective posting to the loan account. The lender's cut-off time, processing method and value-date rules matter.
Before making a large payment, confirm the correct account and whether it will be treated as principal repayment, an advance instalment or another kind of credit. Keep the receipt and check the revised balance. A payment sitting in a linked account may not reduce the loan until the required transfer occurs.
Direct answer: Repaid principal is reusable only when the contract permits redraw and sufficient credit remains available. An interest payment, a successful transfer request or the original sanction amount does not by itself establish how much you can borrow again.
How is interest on a flexi loan calculated?
For a facility that charges daily interest on utilised principal, interest is calculated from the balance outstanding on each day and the applicable annual rate. A balance change alters interest from its effective date. Confirm the day-count convention and how the lender posts interest.
A simplified calculation is:
Interest for a period = outstanding principal × annual rate × days ÷ days in the contractual year.
If the balance changes, calculate each constant-balance period separately and add the results. The following example assumes a 365-day year, simple daily accrual, a constant 12% annual rate and no charges capitalised into principal.
An illustrative month with changing balances
| Period | Outstanding principal | Days | Illustrative interest |
|---|---|---|---|
| First period | ₹1,00,000 | 10 | ₹328.77 |
| After repaying ₹40,000 | ₹60,000 | 10 | ₹197.26 |
| After drawing another ₹20,000 | ₹80,000 | 10 | ₹263.01 |
| Total | — | 30 | ₹789.04 |
The same ₹1,00,000 remaining outstanding for all 30 days would produce approximately ₹986.30 of interest under these assumptions. The reduction is approximately ₹197.26. It arises because ₹40,000 was repaid for ten days and ₹20,000 remained repaid for the next ten days.
This is not an EMI quotation or an APR calculation. The example excludes processing, facility, maintenance and other charges. A lender using different balance dates, day-count rules or repayment allocation may produce a different statement.
Interest rate is different from the interest base
A low annual rate does not answer how much principal attracts that rate. Ask the lender to explain both the percentage and the balance to which it applies. "Interest only on the amount used" should correspond to actual loan-account mechanics, not merely promotional wording.
Also distinguish a charge based on the sanctioned limit from interest on principal outstanding. A facility fee calculated using the limit can be payable even when utilisation is low. That fee does not necessarily mean the lender calculates interest on unused credit, but it still affects cost.
Fixed, floating, flat and reducing are different concepts
Fixed and floating describe whether the interest rate can change. Flat and reducing describe the balance used to calculate interest. A fixed-rate loan can use a reducing-balance calculation; these are not opposing categories.
If the rate floats, ask what benchmark and spread apply, when resets occur, and how a rate change affects payments or tenure. For any product quoted with a flat rate, request the repayment schedule and comparable annualised cost. Comparing percentages without their calculation methods can be misleading.
What happens when the credit limit reduces?
When a dropline limit falls, your borrowing headroom can shrink even if you have made every required payment. If the new permitted limit is below the outstanding balance, the agreement may require a repayment to bring the account within that limit.
Suppose the current ceiling is ₹3,00,000 and principal outstanding is ₹2,40,000. Available headroom is ₹60,000. If the scheduled ceiling falls to ₹2,50,000, headroom falls to ₹10,000 without any new borrowing.
A later ₹30,000 principal repayment would reduce outstanding principal to ₹2,10,000 and create ₹40,000 of headroom at that ₹2,50,000 ceiling. It would not restore the original ₹90,000 of headroom implied by the initial sanction.
Match the limit schedule to future expenses
For phased expenditure, list the expected payment dates alongside the permitted limit on each date. A large initial sanction is less useful if the line reduces before a later payment becomes due. Include both the expected outstanding balance and the next planned withdrawal.
The schedule also tells you how rapidly you must reduce debt. A borrower may be able to afford current interest but still lack the cash needed for a future limit step-down. Ask for the complete schedule rather than a verbal description such as "gradually reducing."
Separate scheduled reductions from lender reviews
A planned dropline reduction is different from a review, suspension or cancellation permitted under the contract. Read the clauses governing renewal, information updates, overdue payments and changes in financial circumstances.
An unused line should not be your only emergency reserve. It is contingent access to borrowing, and its availability may be affected precisely when income becomes uncertain. Keep essential cash needs separate from assumptions about future redraws.
Does an interest-only payment reduce the debt?
No. An interest-only payment normally pays the borrowing cost for that period while leaving principal unchanged. It can reduce immediate cash outflow, but it does not establish a path to becoming debt-free.
For illustration, ₹2,00,000 outstanding at 12% annually produces ₹2,000 of interest over a one-twelfth-year period. Paying that ₹2,000 leaves ₹2,00,000 of principal outstanding. Actual daily-interest bills vary with the number of days and balance movements.
Repayment reality: A low initial payment can coexist with a large future obligation. Before accepting an interest-only phase, identify the first date principal becomes payable and the amount required from that date onward.
Check the transition to principal repayment
Ask for a schedule showing the initial phase, later instalments and final maturity amount. If principal repayment begins later, the remaining time to clear the debt may be shorter. A payment that looks comfortable at the start can rise substantially.
Do not assume that maturity will be extended, the loan refinanced or a fresh facility granted. Those are future credit decisions. A repayment plan should work under the agreement you are actually signing.
Create a principal target even when payments are flexible
Separate the contractual minimum from your own debt-reduction target. If you intend to clear a balance over a particular period, identify the monthly cash you can direct to principal in addition to interest and charges.
For irregular income, plan with dependable receipts rather than the best month. A seasonal windfall can accelerate repayment once received; it should not be the only way to meet a mandatory future instalment. Review the remaining debt after each redraw because a new withdrawal can undo earlier progress.
When can flexibility save money, and when can fees outweigh it?
Flexibility can reduce interest when you genuinely borrow less, borrow later or repay principal earlier than under the alternative. It may not reduce total cost if the facility carries higher rates or fees, or if convenient redraws keep the balance outstanding longer.
The comparison needs the same spending requirement and repayment capacity. Comparing a small flexi withdrawal with a much larger term loan shows the effect of borrowing less, but does not prove that every flexi product is cheaper.
Compare the complete cost of your borrowing pattern
| Cost component | What it means for a flexi borrower |
|---|---|
| Interest on outstanding principal | Depends on balances, dates and rate rules |
| Upfront processing or facility fee | May be calculated on the sanctioned amount rather than initial use |
| Annual or maintenance charge | May continue while the facility remains open |
| Withdrawal-related charge | Can make repeated small drawings expensive if applicable |
| Taxes on applicable charges | Increase the cash cost beyond the quoted fee |
| Prepayment or closure charge | Must be checked against the contract and applicable rules |
| Late or failed-payment charges | Add cost if required payments are not made as agreed |
An illustrative ₹6,000 annual facility fee is equivalent to 12% of an average utilised balance of ₹50,000 before interest. That 12% is a simple fee-to-balance comparison, not a regulatory APR. It demonstrates why an expensive line used only lightly can disappoint.
For a facility kept open mainly as a backup, compare its ongoing cost with the benefit of access. A smaller limit or another arrangement might meet the same need more economically. Conversely, a slightly higher headline rate may be acceptable if actual utilisation is brief and other charges are low.
Request comparable scenarios rather than a single EMI
Ask for the cost of three plausible patterns: your expected drawings, a slower repayment scenario, and a scenario where you need most of the limit. Include planned closure timing. A single EMI calculated on full utilisation may not describe a changing-balance facility accurately. For any portion that follows a fixed instalment schedule, you can test amount, rate and tenure scenarios with the Finbros EMI Calculator.
The RBI's current NBFC conduct directions require a KFS for covered retail term loans. A flexi label alone does not establish that a facility is a term loan. Ask which disclosures apply to the actual structure and obtain written cost and repayment terms.
How does a flexi facility compare with other borrowing?
Compare the mechanics of the actual offers. A personal term loan, an overdraft and a card can each be suitable for a different payment pattern, and none is universally cheapest.
| Question | Drawdown-based flexi facility | Standard personal term loan | Credit card |
|---|---|---|---|
| How is credit used? | Drawings within an available limit | Usually a lump-sum disbursal | Purchases and other permitted transactions |
| Can repaid principal be reused? | Only if the agreement permits | Usually requires fresh borrowing | Generally within the active card limit |
| What drives interest? | Utilised balance and contractual method | Outstanding loan balance and repayment schedule | Transaction type, payment behaviour and card terms |
| How clear is the repayment end date? | Depends on redraws and structure | Defined by the repayment schedule | Can extend if balances revolve |
| Main comparison risk | Fees and repeated utilisation | Borrowing more or earlier than needed | Mistaking minimum payment for full repayment |
Flexi loan versus a standard personal loan
A term loan is easier to evaluate when you need a known amount once and can make regular repayments. Its fixed schedule can provide discipline. A drawdown facility can be useful when the amount or timing is uncertain, but you must monitor it more actively.
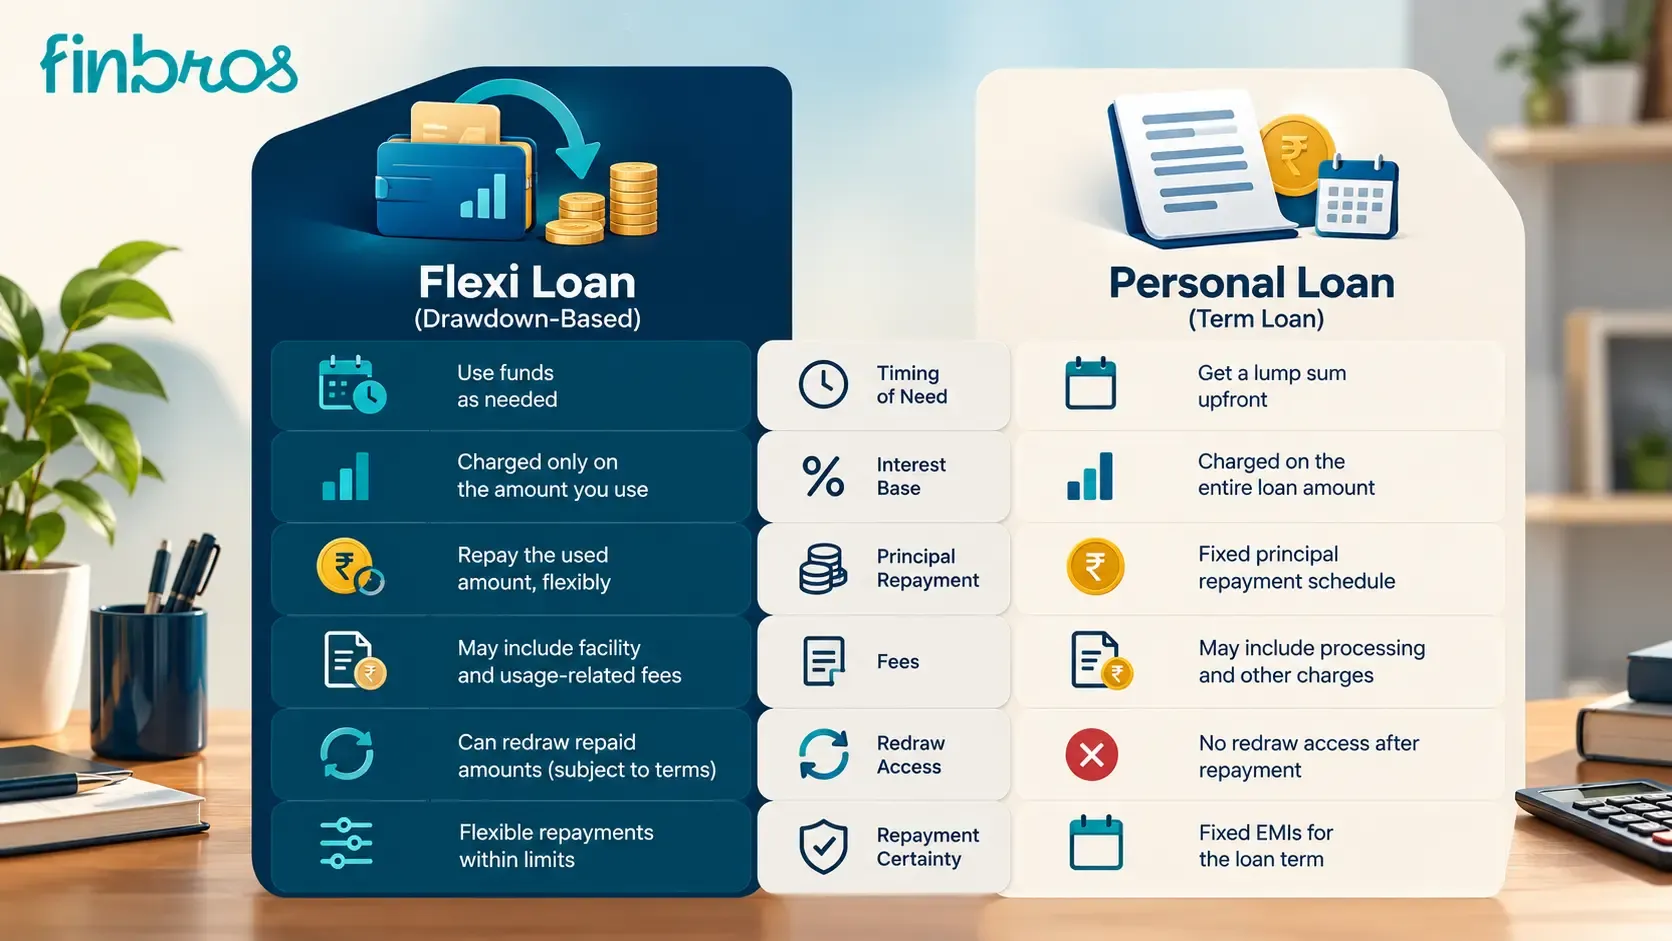
A standard reducing-balance personal loan charges interest on outstanding principal as it is repaid, not permanently on the original amount. The relevant distinction is when principal is disbursed and repaid. Avoid comparisons that incorrectly describe all personal loans as charging interest on the original principal throughout. If a single disbursal fits your need better, compare personal loan options on the same total-cost basis.
Flexi loan versus an overdraft
An overdraft may already provide many of the features advertised as flexi: access within a limit and interest linked to utilisation. The overlap means the names alone are poor grounds for comparison.
Check whether an account linkage, collateral requirement, review date or demand-repayment clause changes the arrangement. If an asset is pledged, consider the consequence of non-payment as well as the interest rate. Do not infer that a secured product is preferable solely because the rate is lower.
Flexi loan versus a credit card
A card can be economical for eligible purchases when the full statement balance is paid according to the issuer's interest-free-period conditions. Cash withdrawals, revolving balances and instalment conversions can carry different costs and rules.
A flexi withdrawal should therefore be compared with the specific card transaction you would otherwise make. Comparing a loan with expensive revolving card debt does not establish that it beats an eligible purchase paid in full. Rewards are secondary to the total financing cost.
How do lenders assess whether a limit is affordable?
Lenders assess whether your income, existing obligations and repayment history support the requested exposure. A high proposed limit is not justified simply because you plan to use only a small part of it; access to additional borrowing creates potential repayment risk.
Income documents establish the amount and consistency of earnings. Bank statements help show actual receipts and existing commitments. Credit history provides evidence of past borrowing behaviour. For self-employed applicants, business receipts need to be distinguished from money available after operating costs and taxes.
Why income timing matters as much as income size
A borrower with substantial but irregular receipts may struggle with a fixed payment date. Map when reliable money arrives against interest debits, principal instalments and limit reductions. An annual income figure can hide a difficult month.
Consider a freelancer who expects a large invoice payment but cannot control the customer's approval process. A flexi facility may bridge timing, but delayed payment does not postpone the loan's due date automatically. The borrower needs another credible way to meet required payments during the delay.
Why a credit score is only one input
A score summarises aspects of credit history; it is not a universal approval threshold or a guarantee of pricing. Recent missed payments, existing debts, incomplete records and the requested amount can all affect assessment.
Distinguish an indicative eligibility enquiry from a formal lender application. Ask what credit enquiry will occur and when consent is sought. Repeated applications to compensate for an unsuitable profile may add enquiries without fixing the underlying repayment problem.
What documentation should clarify
Submit the documents the actual lender accepts for identity, address, income and banking checks. Do not assume one named document is the only possible KYC route or that every applicant needs the same statement period.
The purpose is a consistent picture of the borrower and cash flow. If your income has recently changed, explain it accurately rather than relying only on old records. Approval based on outdated income is not evidence that the new payment obligation will be comfortable.
What should happen between approval and the first withdrawal?
Before drawing funds, you should be able to identify the lender, understand the agreement, access the repayment schedule and confirm how the facility operates. An approved limit and a completed disbursal are different events.
Save the sanction terms, fee schedule and account instructions. Confirm when interest begins, whether activation itself triggers charges, and whether money is advanced automatically. Check that the repayment mandate uses an account you monitor and that the first due date is clear.
Test the important questions against the contract
Ask the lender to point to the clauses answering these questions:
- Is the full amount disbursed, or do I request each drawing?
- Does principal repayment restore access, and when?
- Can the permitted limit reduce, and on which dates?
- What must I pay each month even if I do not redraw?
- What happens at the end of an interest-only phase?
- What amount must be cleared at maturity?
- How do I close the facility completely?
A useful answer refers to your offer, not a general explanation of the product. If a salesperson's statement differs from the agreement, obtain clarification before accepting or drawing funds.
Understand digital exit rights
For covered NBFC digital loans, the RBI's current credit-facility directions provide a cooling-off exit by repaying principal and proportionate APR; a disclosed reasonable one-time processing fee may be retained. Check the applicable period and procedure. This does not make later redraws automatically refundable.
Do not use the cooling-off option as a substitute for understanding the product first. You still need access to the money required to exit, and the contractual process matters.
How should you manage, prepay and close a flexi loan?
Manage the facility as an active debt account. Track the principal balance, required payment, current limit and remaining term together. Looking only at the amount available to withdraw can conceal a balance that is not falling.
Before choosing: Compare the expected borrowing pattern, total fees, principal-repayment schedule and redraw rules. A facility is affordable only if you can meet its required payments without depending on another withdrawal from the same line.
Use each statement to reconcile the debt
Check opening principal, new drawings, interest, fees, payments, principal allocation and closing principal. If something does not reconcile, raise it promptly with supporting transaction records.
Maintain enough funds for required debits, including a month with lower income. If repayment becomes difficult, contact the lender before the due date and ask what options are available. A discussion does not change the contract unless the lender agrees to revised terms.
Distinguish partial repayment from closure
Paying principal down to zero may leave the facility open. Accrued interest, an annual fee or another charge may still be due, and account closure can require a separate request.
Ask for a dated closure quotation and instructions, pay through the designated route, and obtain closure confirmation. Retain the final statement and check that future mandates and facility charges are handled correctly. Do not cancel a repayment mandate while genuine dues remain outstanding.
Do not assume every flexi loan has free foreclosure
The RBI's current commercial-bank conduct directions prohibit prepayment charges on covered floating-rate non-business loans to individuals sanctioned or renewed from 1 January 2026. Fixed-rate, business-purpose and other facilities require separate checks. The word flexi is not a fee exemption.
For an overdraft-style arrangement, also ask whether closing before the due date and choosing not to renew are treated differently. Request the amount and basis of any proposed charge in writing.
When is a flexi loan suitable, and when should you reconsider?
A flexi facility may suit staged expenses and temporary gaps when you have a credible repayment source, understand the changing balance and will actually use its features. It is less suitable when repeated access encourages spending or when required principal reduction exceeds dependable cash flow.
| Borrowing situation | Decision implication |
|---|---|
| Several payments with uncertain timing | Compare genuine drawdown access with a lump-sum loan |
| One fixed payment needed immediately | A term loan may be simpler; compare complete costs |
| Expected receipts are delayed but reliable | Test whether required payments remain affordable if the delay grows |
| Regular expenses already exceed income | Reusable credit can prolong the shortfall rather than resolve it |
| The line is mainly an emergency backup | Assess maintenance cost and the possibility of restricted access |
| You prefer predictable debt reduction | A fixed repayment structure may be easier to manage |
The strongest case for flexibility is a specific timing problem with a clear repayment plan. The weakest case is borrowing because the limit is available. A facility can solve when money arrives; it cannot create the income needed to repay it.
Frequently asked questions
Can I repay and redraw on the same day?
Only if the lender permits it and recognises the principal repayment in time. Processing cut-offs, holds, overdue amounts and the current limit can affect availability. Confirm the displayed available balance before committing to a payment that depends on the redraw.
Will a refund into my savings account reduce flexi interest?
Not automatically. If that account is separate from the loan, the refund may need to be transferred through the lender's repayment process. Interest changes when the loan balance is reduced under the contract, not simply when money reaches any account you own.
Can the available limit fall even when I have paid on time?
Yes, if the agreed limit schedule reduces over time or another contractual review changes access. Timely payment and a constant borrowing ceiling are separate matters. Keep the scheduled limit alongside your repayment plan.
What if I never use the sanctioned facility?
You may still incur activation, processing or maintenance charges if the agreement provides for them. Ask whether accepting the offer activates the facility or causes disbursal, and what cancellation or closure involves. Zero utilisation does not necessarily mean zero cost.
Is transferring the outstanding balance to another lender always beneficial?
No. Compare the new rate and fees, the old facility's closure cost, any change in tenure and the redraw features you would lose. A lower monthly payment caused by extending the debt can increase total cost even when the new rate is lower.
Can I use a standard EMI calculator for a flexi facility?
Only for the parts that follow a standard amortising schedule. A changing-balance line or interest-only phase needs calculations based on actual drawings, repayments and contract rules. A term-loan EMI is not a reliable forecast of every flexi payment.
Make the borrowing pattern the starting point
A flexi loan is useful when its withdrawal and repayment mechanics fit a real funding need. Check the current limit, the balance that attracts interest, the way payments reduce principal and the conditions for borrowing again. Then compare fees and the full repayment path with a simpler term loan. A low initial payment or a large sanctioned limit should not decide the choice. If the structure fits your cash flow, explore Finbros flexi loan options and assess the actual lender offer against the borrowing pattern you expect to follow.
Table of Contents