

What Is a Short-Term Loan and How Does It Work?
A short-term loan is credit that must be repaid over a relatively brief period. The exact boundary depends on the product: a Finbros short-term personal-loan offer may use a few months to a year, while other lenders describe short-term credit more broadly. The important feature is the repayment horizon, not a universal number.
Short tenure can reduce the calendar time you pay interest, but it raises the EMI for a given amount. This makes affordability the central question: can you clear a temporary gap without using another loan to meet the payment?
Key takeaways
- “Short-term” has no universal tenure: products range from 30-day bullet repayments to EMI loans of around a year, so compare the actual structure.
- A shorter tenure can reduce total interest but raises the EMI; the payment must fit essentials without relying on another loan.
- Test the repayment source against a delay of one or two payment cycles before borrowing.
- Compare the complete rupee cost, including processing fees, taxes, late charges and add-ons, not just the rate or the EMI.
- Taking a new loan to pay an old EMI, rolling over a bullet repayment or using several apps for the same gap creates a debt cycle.
- Approval is not evidence of affordability; the lender assesses its own risk while you remain responsible for the household budget.
Direct answer: A short-term loan provides a fixed amount for a time-bound need and is repaid through EMIs or, for some products, a single maturity payment. The rate, fees, tenure and lender assessment determine whether its speed is worth the higher monthly pressure.
What is a short-term loan used for?
Borrowers commonly consider short-term credit for an urgent bill, a temporary income timing gap, a repair, a small business cash-flow need or another expense with a credible repayment source. A loan should bridge a defined gap rather than fund recurring living expenses indefinitely.
The same label can cover unsecured personal credit, gold-backed credit, an overdraft, a payday-style product or short-tenure business finance. Compare the actual structure. A 30-day bullet repayment creates a different risk from a 12-month amortising EMI even if both are called short-term.
How does a short-term loan work?
The lender reviews identity, income, existing obligations, credit history and repayment capacity. If approved, the agreed amount is disbursed and the borrower repays according to the schedule. An EMI normally contains interest and principal; a bullet product may leave principal due at maturity.
A repayment timeline
- Identify the amount and the date the repayment source is expected.
- Compare offers by total repayment, EMI, fees, due dates and early-closure terms.
- Submit KYC, income and banking information through the lender's verified process.
- Read the sanction letter, KFS where applicable, agreement and amortisation schedule.
- Set aside each due amount before discretionary spending.
- Close the account formally and retain closure confirmation.
Fast processing does not remove the need to read terms. A missed short-tenure EMI can consume a large share of monthly income and lead to charges or adverse credit reporting.
Why the same principal feels more expensive each month
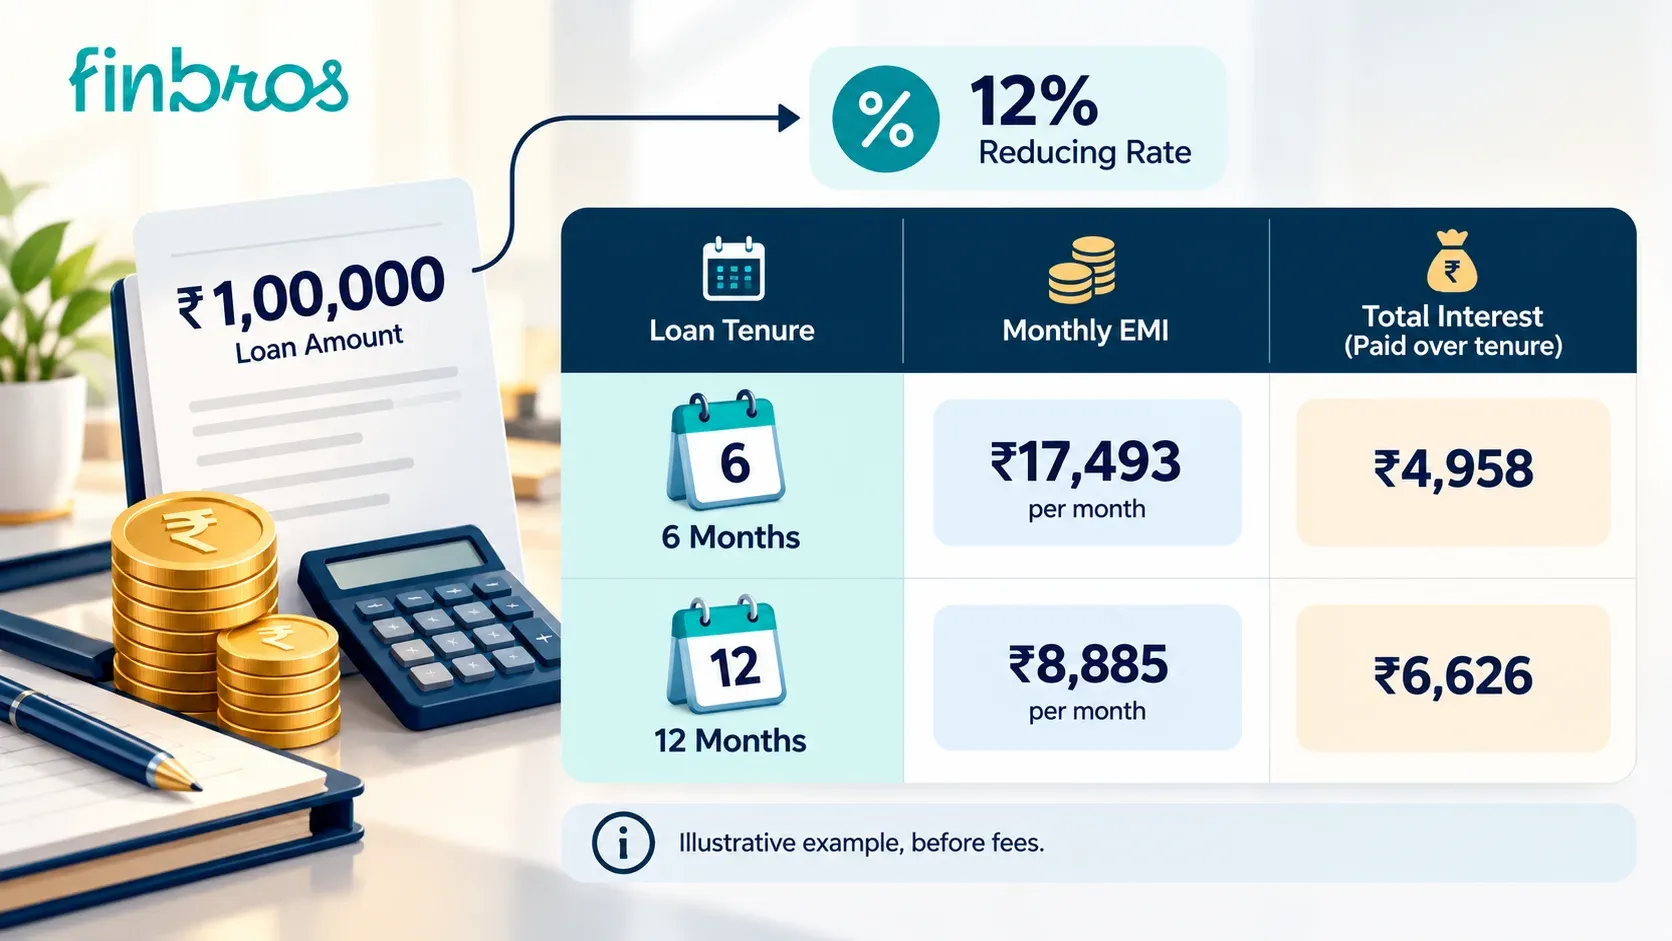
At an illustrative 12% reducing rate, ₹1,00,000 over six months produces a payment of about ₹17,255 and total scheduled repayment of about ₹1,03,529. Over twelve months, the payment falls to about ₹8,885 but scheduled repayment rises to about ₹1,06,619, before fees. These are calculations, not quotes.
| Choice | Monthly pressure | Scheduled interest under the illustration |
|---|---|---|
| 6 months | Higher | About ₹3,529 |
| 12 months | Lower | About ₹6,619 |
A longer term can be the safer cash-flow choice if the six-month EMI would affect essentials. Lower total interest is not useful if the payment is unaffordable.
How should you test affordability?
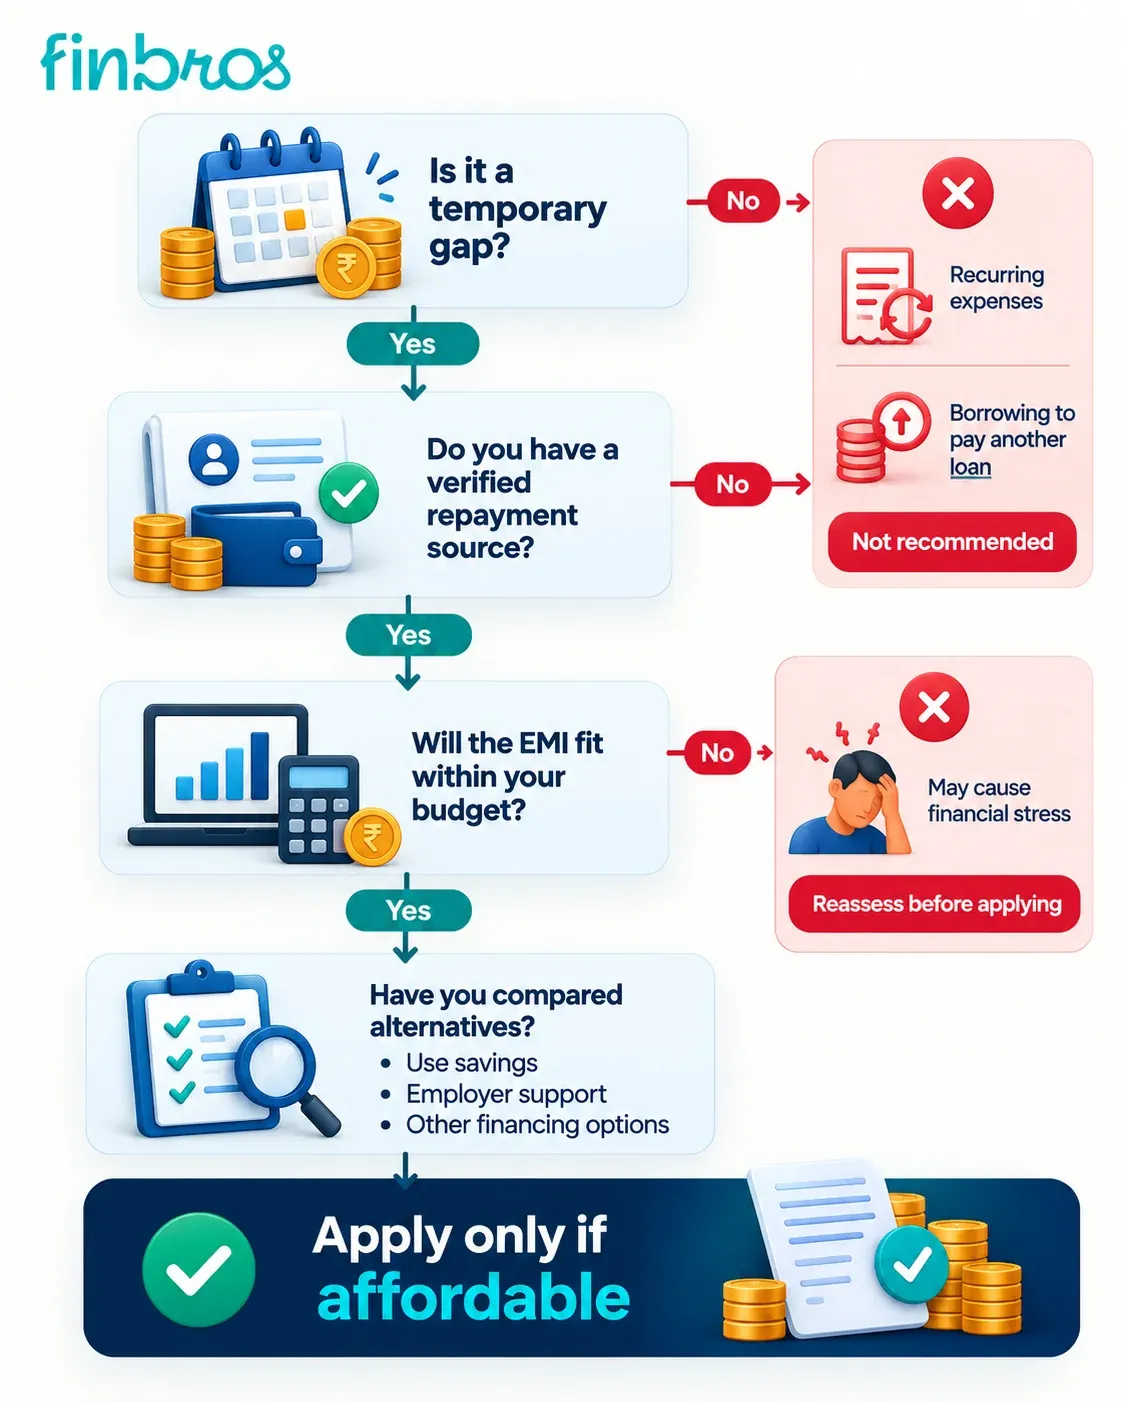
Start with dependable monthly income and subtract essential household costs, existing EMIs, taxes and a buffer for disruption. The proposed EMI should fit without relying on a bonus, uncertain invoice or another credit line.
Use a repayment-source test
Write down the exact source expected to repay the loan: salary, reimbursement, receivable, sale or another known inflow. Then test a delay of one or two payment cycles. If the plan fails under a reasonable delay, the loan may not be a suitable bridge.
Do not treat approval as evidence of affordability. Lenders assess their risk using their own policies; you remain responsible for the household budget.
Watch for the debt cycle
A short-term loan becomes dangerous when the borrower takes a new loan to pay an old EMI, rolls a bullet repayment forward or uses several apps for the same gap. The first loan may look small, but simultaneous due dates increase the total obligation and can reduce future eligibility.
If recurring expenses exceed income, shortening each loan does not solve the problem. Reduce the expense, negotiate the payment, increase dependable income or seek regulated advice before adding more debt.
What is the complete cost?
The complete cost can include interest, processing fee, tax on charges, late or bounce charges, insurance or add-ons, documentation costs and permitted prepayment charges. Some very short products advertise a periodic fee that looks small until annualised.
The RBI's KFS rules define APR as the annual cost of credit including associated charges and require a standardised KFS for covered retail and MSME term loans. Read the KFS and repayment schedule; do not compare a monthly fee with an annual rate without converting the basis.
Cost checklist
| Item | What to confirm |
|---|---|
| Interest method | Reducing, flat, daily or another method |
| Total repayment | Principal plus scheduled interest and disclosed charges |
| Processing fee | Amount, tax and whether deducted before disbursal |
| Due dates | First payment, frequency and mandate |
| Late charges | Fixed, percentage or penal interest basis |
| Prepayment | Eligibility, lock-in and charge |
| Closure | Statement, no-dues letter and mandate handling |
A low EMI can hide a long tenure. A low rate can hide a high fee. Use the total rupee cost for the same amount and repayment period. You can test amount, rate and tenure scenarios with the Finbros EMI Calculator.
What do lenders assess?
Lenders generally consider income stability, employment or business profile, existing obligations, bank conduct, credit history and the requested amount. Thresholds vary; a score or income number from one lender is not universal.
Because the EMI is concentrated into a shorter period, current cash flow matters. Self-employed applicants may need to show business receipts, tax records and bank statements. A clean file cannot guarantee approval, but inconsistent documents can slow or weaken an assessment.
Formal application versus indicative check
An eligibility calculator or soft enquiry may provide an indication. A formal application can involve a hard enquiry and lender-specific underwriting. Ask when consent is taken and which lender will assess the application. Applying repeatedly to solve a time problem can create more enquiries without making repayment safer.
Short-term versus longer-term borrowing
Choose the shorter term when the payment is comfortable and the repayment source is dependable. Choose more time when the shorter EMI would undermine essentials, while recognising that total interest can rise.
| Question | Shorter tenure | Longer tenure |
|---|---|---|
| Monthly EMI | Higher | Lower |
| Time in debt | Shorter | Longer |
| Total interest | Often lower | Often higher |
| Main risk | Cash-flow strain | Cost and prolonged obligation |
The correct comparison holds the amount and rate assumptions constant. Compare actual offers rather than assuming every short-term product is cheaper. If a longer repayment horizon suits the need better, compare personal loan options on the same total-cost basis.
What should you do before applying?
Confirm the amount you need, the earliest payment date, the source of repayment and your maximum comfortable EMI. Check whether a savings buffer, employer advance, overdraft or negotiated bill is less expensive and safer.
If a short-term loan remains appropriate, compare at least the complete cost, payment schedule, lender identity, grievance route and closure procedure. For digital lending, use a regulated lender's verified channel. RBI digital-lending directions address disclosures, cooling-off and grievance redressal, while an app's presence in a directory should not be presented as an RBI endorsement.
When should you avoid it?
Reconsider when the need is recurring, the EMI would reduce essentials, repayment depends on uncertain income, or the loan would pay another loan. Also reconsider a bullet product if you have no committed lump sum at maturity.
Short-term borrowing can be appropriate for a temporary mismatch. It is a poor substitute for an emergency fund, stable budget or sustainable income.
Frequently asked questions
What is the maximum tenure of a short-term loan?
There is no single universal maximum. The relevant product may run for weeks, months or around a year, while broader market definitions can extend further. Use the lender's written tenure and repayment schedule.
Are short-term loans always cheaper?
No. They may reduce total interest by ending sooner, but fees and a higher EMI can increase the effective burden. Compare total cost and affordability.
Can I get one without collateral?
Many short-term personal loans are unsecured, but secured gold, deposit or other facilities also exist. Unsecured does not mean free or guaranteed.
What if I cannot pay the final lump sum?
Contact the lender before maturity and ask what documented options exist. Do not assume a rollover is approved; a new loan can cost more and prolong the debt.
Can self-employed borrowers apply?
Yes, where the lender accepts their income and business documents. Approval depends on the complete assessment, not employment label alone.
Does a rejected application hurt CIBIL?
The rejection itself is not a loan balance. A formal application may create a credit enquiry, and many enquiries in a short period can affect how lenders view the file. Ask the lender about the enquiry stage.
Match the repayment horizon to the cash-flow problem
A short-term loan is useful when the gap is genuinely temporary and the repayment source is credible. Compare the complete cost, test the EMI against essentials and read the schedule before signing. Finbros can help you compare short-term loan offers, but the selected lender decides approval and terms.
Table of Contents