

What Is a Travel Loan and How Does It Work?
A travel loan is borrowing used for flights, accommodation, packages, visas, travel insurance and other trip costs. In India it is usually an unsecured personal loan marketed for travel rather than a separate universal loan category. The borrower receives funds, pays the trip cost and repays the balance with interest and charges through EMIs.
The right decision depends on the full financed trip cost and the EMI after the trip is over. A holiday is temporary; the loan can remain for years. Borrow only the funding gap you can repay without weakening emergency savings or essential spending.
Key takeaways
- A travel loan is usually an unsecured personal loan marketed for trips, not a separate universal loan category; check the actual end-use terms.
- Budget the whole trip first, deduct savings and other confirmed funding, and borrow only the remaining gap rather than the lender’s maximum.
- A longer tenure lowers the EMI but raises total repayment, so the trip costs more than its booking price once financed.
- Compare total cost, including processing fees, taxes, late charges and prepayment terms, not just the monthly EMI.
- A cancelled booking and loan closure are separate processes; keep paying EMIs until the lender confirms any refund adjustment.
- Test the EMI as if the trip has already ended: if it would force cuts to essentials, reduce the trip or wait.
Direct answer: A travel loan lets a borrower fund a planned or urgent trip now and repay it later. It can be reasonable for a defined, affordable trip, but a lower EMI can conceal a higher total cost and discretionary travel should not depend on uncertain future income.
What can a travel loan pay for?
Depending on lender terms, the funds may cover flights, hotels, tour packages, visas, travel insurance, foreign-exchange needs, local transport, cruises or a honeymoon. Confirm the actual end-use terms; many personal loans are unrestricted, while a linked booking or instalment product may be narrower.
Create a trip budget before deciding the loan amount. Separate essential travel, optional upgrades, shopping and a contingency. A lender's maximum is not a trip budget.
How does a travel loan work?
The lender assesses the borrower's identity, income, credit history, existing obligations and repayment capacity. On approval, a lump sum may be credited to the borrower or applied through a booking partner. The borrower then makes scheduled repayments under the offer and agreement.
A practical travel-finance sequence
- Price the trip using cancellable or refundable terms where available.
- Deduct savings, rewards, employer reimbursement and other confirmed funding.
- Calculate the remaining gap and a post-trip EMI budget.
- Compare rate, fee, APR, tenure, due date, prepayment and disbursal conditions.
- Read the KFS or equivalent cost document and the agreement.
- Borrow only after testing the EMI against ordinary monthly expenses.
"Instant" describes a lender process, not a guarantee. Verification, lender policy and complete documents affect timing.
Illustrative trip-cost example
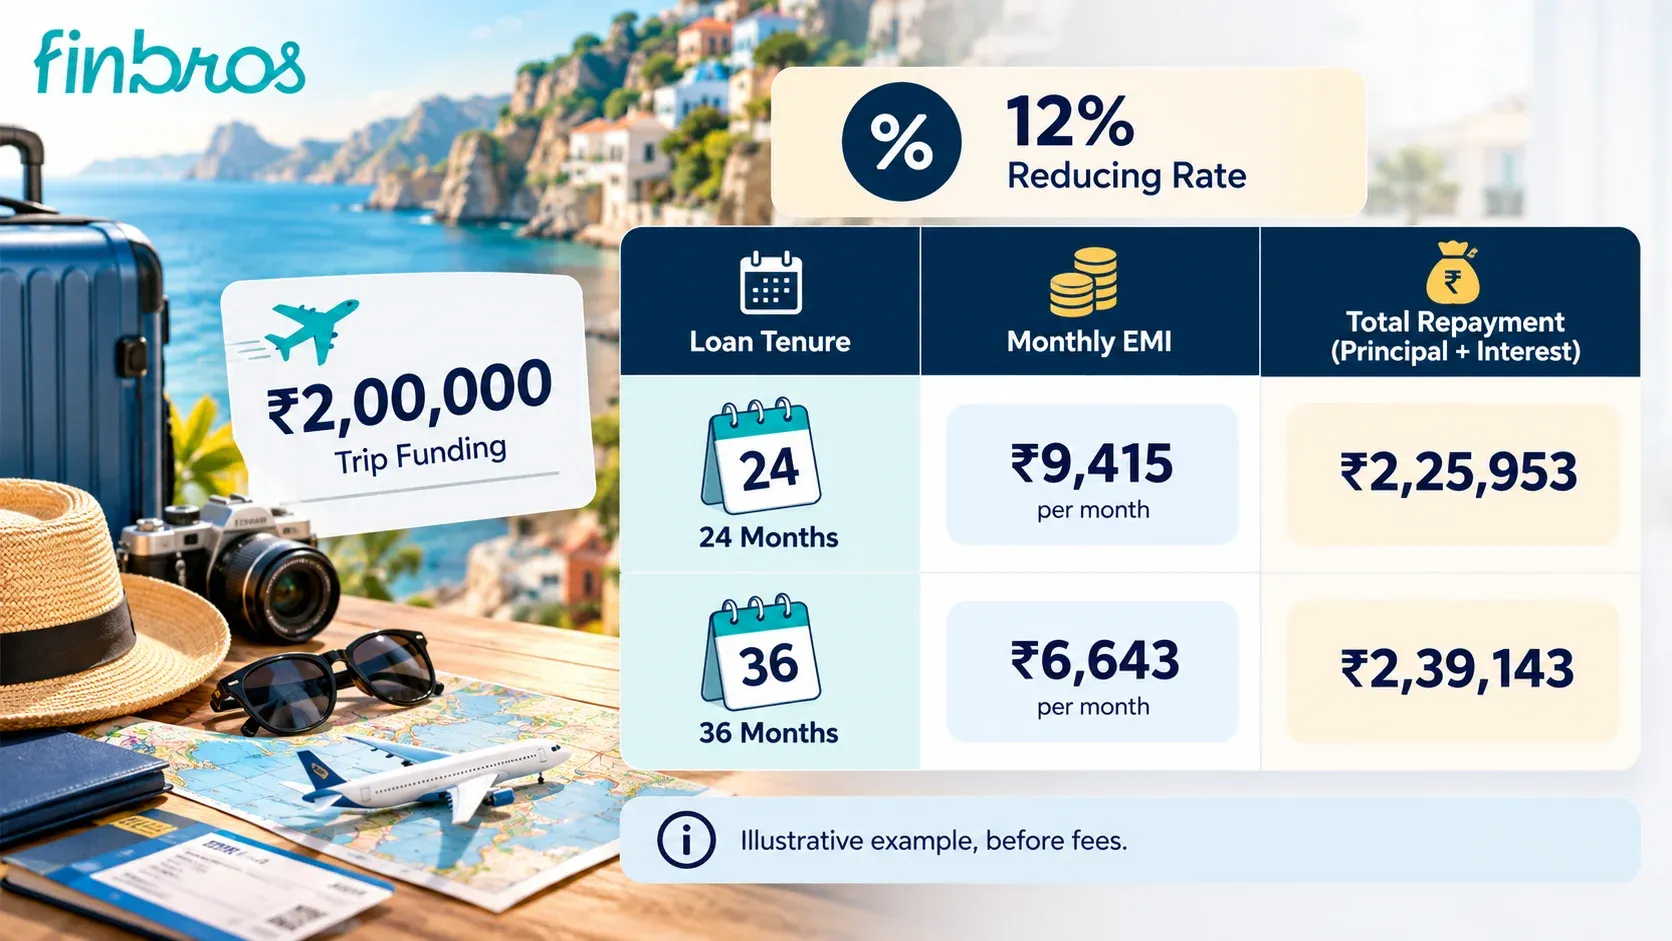
Suppose a borrower finances ₹2,00,000 for 24 months at an illustrative 12% reducing rate. The EMI is about ₹9,415 and scheduled repayment about ₹2,25,953 before fees. If the term extends to 36 months, the EMI falls to about ₹6,643 but scheduled repayment rises to about ₹2,39,143. These figures are calculations, not offers.
| Tenure | Illustrative EMI | Scheduled repayment (before fees) |
|---|---|---|
| 24 months | About ₹9,415 | About ₹2,25,953 |
| 36 months | About ₹6,643 | About ₹2,39,143 |
The trip therefore costs more than its booking price. Add processing fee and tax, then ask whether the household still wants the trip at the financed price.
How should you budget the trip before borrowing?
Use four buckets: confirmed trip cost, likely variable cost, existing funding and repayment reserve. Include currency movement for international travel, baggage, transfers and insurance. Do not assume a refund or reward will arrive before an EMI is due.
Borrow for the gap, not the maximum
A smaller loan reduces interest and the post-trip obligation. If savings cover flights, borrowing only for accommodation may be safer than financing everything. If the trip depends on a maximum loan, reconsider the itinerary or timing.
Ask whether the trip is discretionary or urgent
A family emergency, necessary visit or employer-required trip may have a different value from an optional upgrade. The distinction does not decide the application, but it should affect how much financial risk you accept. A luxury upgrade should not be financed at the same price as an unavoidable journey.
What affects approval and cost?
Income stability, existing EMIs, credit history, banking conduct, employment or business profile and requested amount can affect the lender's decision and pricing. A higher score can help, but no single score or income threshold applies to every lender.
A formal application may create a hard enquiry. Ask whether an eligibility check is indicative or a lender application, and avoid sending multiple applications merely to compare basic terms.
Documents and travel evidence
KYC, salary slips, tax records and bank statements are commonly used to verify identity and income. An itinerary or quotation can help you budget, but a standard personal loan may not require it. Submit only what the verified lender asks for.
How much does a travel loan cost?
Compare interest, processing fee, tax, late charges, failed-payment charges, add-ons and prepayment terms. The RBI KFS framework defines APR as the annual cost including associated charges for covered loans. A monthly EMI is only one part of the decision.
| Cost item | Travel implication |
|---|---|
| Interest | Extends the trip's cost beyond booking price |
| Processing fee and tax | Increases upfront or financed cost |
| Foreign exchange | Can change the amount you need for international travel |
| Cancellation/refund | May leave a loan outstanding after a trip changes |
| Late fee | Adds cost after a missed payment |
| Prepayment | Matters if a bonus or reimbursement arrives later |
Before booking, model the trip cost with the loan and without it. The relevant question is whether the financed version remains worth the repayment obligation. You can test amount, rate and tenure scenarios with the Finbros EMI Calculator.
Travel loan versus card, savings and other options
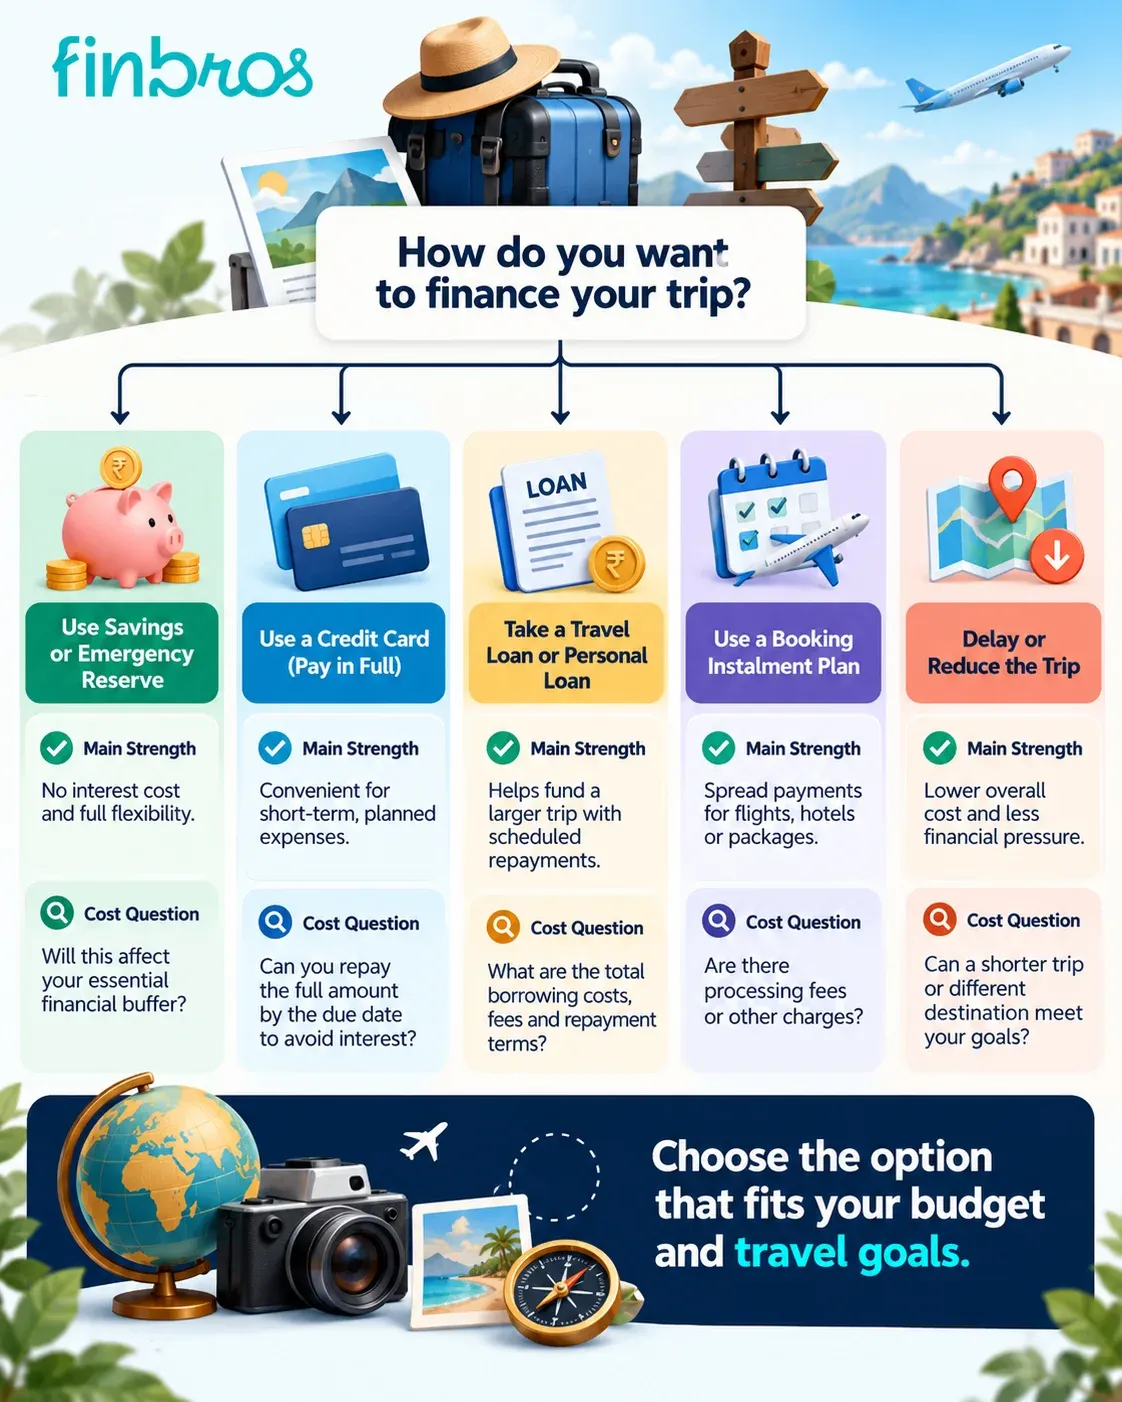
A credit card may offer rewards or an interest-free period when the full statement is paid; revolving a balance can be costly. Savings avoid interest but should not deplete an emergency reserve. A booking instalment plan may have different fees and cancellation rules. Compare the specific offers.
| Option | Main strength | Main check |
|---|---|---|
| Savings | No borrowing cost | Preserve emergency liquidity |
| Credit card paid in full | Convenience and possible rewards | Can you clear the statement? |
| Travel/personal loan | Fixed EMI and larger funding | Total repayment and tenure |
| Booking instalment | May align with a specific vendor | Cash price, fees and cancellation |
| Delay or reduce trip | Avoids financing cost | Practicality and urgency |
If a fixed EMI suits the gap, compare personal loan options on the same total-cost basis.
What can go wrong?
Borrowers may finance upgrades, shopping or the entire maximum budget, then face the EMI after the experience is over. A cancelled booking may produce a refund delay while the loan continues. A currency movement can also increase the funding gap.
Read the cancellation and refund process. Ask how a merchant refund is applied to the loan and whether interest continues until the lender receives it. Keep enough cash for the first EMIs before travelling.
When is a travel loan suitable?
It may suit a planned, time-sensitive or necessary trip when the gap is clear, the EMI fits ordinary cash flow and the total financed cost is acceptable. It is usually unsuitable for an impulse holiday, a luxury upgrade or a trip that would require another loan to repay this one.
A simple test is to imagine the trip has ended but the EMI remains. If the monthly payment would force essential cuts, reduce the trip or wait.
Frequently asked questions
Is a travel loan the same as a personal loan?
Often. Many travel loans are personal loans positioned for a particular purpose. Compare the actual lender terms, pricing and end-use conditions.
Can I use it for an international trip?
Potentially, subject to lender terms and lawful payment arrangements. Budget exchange-rate movement, insurance, visa and cancellation costs before borrowing.
Is a travel loan better than using a credit card?
It depends on repayment behaviour. A card paid in full may avoid interest and offer rewards; a fixed loan may be more predictable for a larger balance. Compare the specific total cost.
Can I prepay a travel loan?
Possibly, depending on the contract and applicable lender rules. Check the written prepayment clause before assuming a future bonus can close the loan cheaply.
What if my trip is cancelled?
Contact the travel provider and lender. A booking refund and loan closure are separate processes; continue meeting due payments until the lender confirms the adjustment.
How much should I borrow for a honeymoon?
There is no responsible universal amount. Budget the complete trip, deduct dependable funding and test the remaining EMI against post-marriage household costs.
Price the trip with its repayment attached
A travel loan can spread a defined cost, but it cannot make an unaffordable trip affordable. Confirm the funding gap, compare complete costs and keep repayment capacity after returning home. Finbros can help you compare travel loan options after you know the amount and EMI your budget can carry.
Table of Contents